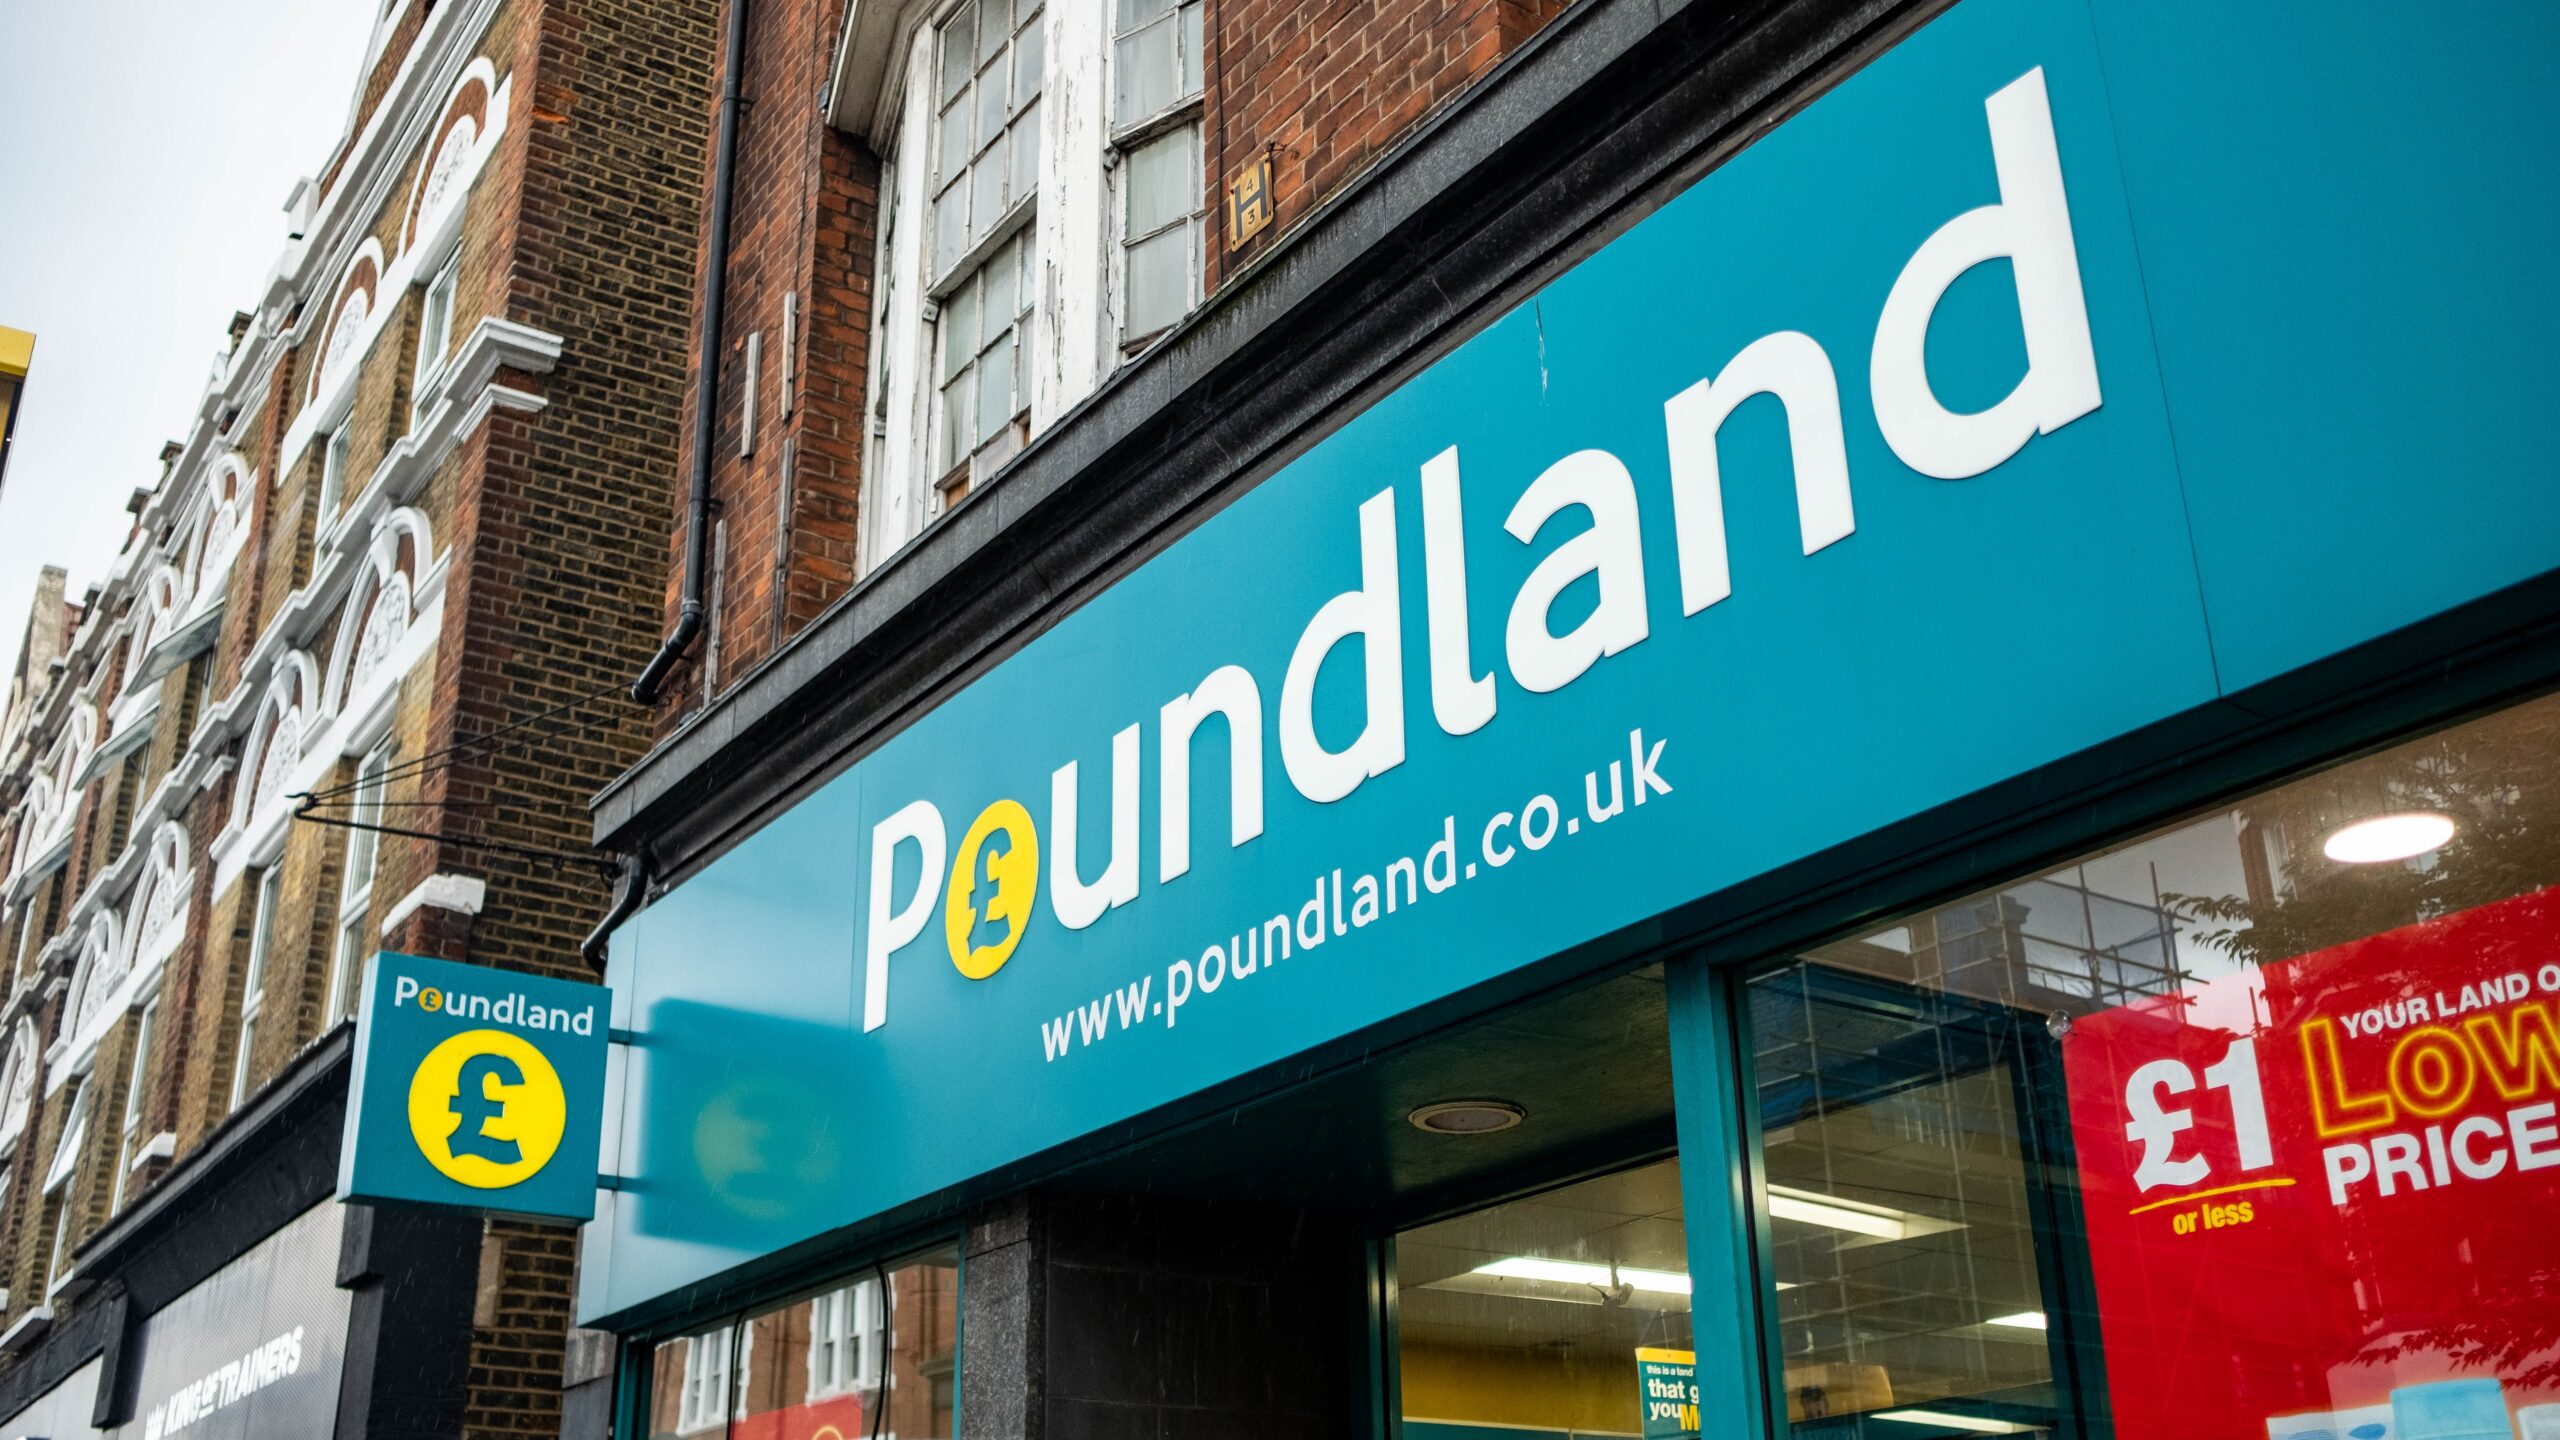
Poundland is a much-loved national asset. Not only does it employ 30,000 people in its stores and supply chains, but in the middle of a cost-of-living crisis it provides a vital lifeline for millions of families who depend on low-cost goods.
But like much of our high street, it has fallen prey to the predations of a ruthless private equity and venture capital industry determined to make the biggest, fastest buck possible, generally with the same tactic: overloading a business with debt in ways that leave it very vulnerable when trading conditions change. Examples include Asda, Morrisons, WHSmith and TG Jones, along with The Body Shop.
Wolves at the door
Across the retail and restructuring industry, seasoned players are aghast at the way in which Gordon Brothers have sought to practically manufacture an insolvency from which they profit greatly.
But when we have the wolves of Wall Street running amok on the British high street, it gets harder to regenerate flourishing local economies that serve and employ local people and help foster growth in every postcode.
Andy Burnham has quite rightly called time on the economics of neoliberalism that underlie this particularly rapacious brand of capitalism. But this wider story, which my committee is investigating, underlines why three reforms should now be considered.
Balancing shareholder, creditor and worker interest
First, we must change section 172 of the Companies Act, which places shareholders’ interests at the heart of directors’ duties. This exorbitant privilege of shareholder primacy has long been a problem and is in sharp contrast to company law in countries like Germany, which allows a more balanced approach to considering the interests of shareholders, creditors—and workers. By reforming corporate governance laws to allow workers on boards, we could also enshrine the position of leaders with a longer-term perspective.
Pension reform
Second, we should reform the laws around fiduciary duties for pension fund trustees to make it clear that they can consider the long-term gains of their investments, rather than simply focus on maximising short-term profit, come hell or high water. As we park more and more of our pension assets in the venture capital industry, this reform—which the government is now consulting on, following my amendment to the Pensions Bill—is essential.
True transparency
But third, we need wholesale accounting reform to ensure that there is real transparency and, potentially, proper stress tests that kick in before shareholders and investment funds are allowed to overload a business with debt that they often supply directly, as is the case with Gordon Brothers. This tactic allows investors to extract what are in effect proxy dividends as debt repayments, call time on a business whenever they like and then take the lion’s share of the proceeds from breaking it up in a wrecker’s yard, flogging off the components to the highest bidder.
Transforming the economic behaviour of the last forty years will not be easy, and it will take time. But if we want to avoid a repeat of the Poundland episode, especially as we head into the economic turbulence that AI will doubtless bring, it is time to rewrite the rules of our market.